History Rhymes!

Every Bull market is led by different heroes. The ones who led the last bull market rarely contribute on the upside. We have all heard this multiple times. However, it’s interesting to see this playing out day in and day out on screen. What is happening to the HDFC group stocks or the Bajaj Twins is not totally unexpected.

Markets have fallen in line with the global markets. The US tech stocks which were the darlings leading up to the end of last year have been butchered. Multiple fancied stocks have fallen over 75% while the revered FAANGs have not been left unscathed either- Netflix has gone from 700 to 175, Facebook/ Meta is down 50% while Amazon and Google are down a third each. Even Apple is down more than 20%.

Now add to this the fact that Adani is all set to take over Ambuja-ACC combined and you have an entire episode of 2007-08 playing out with Tata Steel acquiring Corus and Tata Motors acquiring JLR.

What I believe is that a churn is happening in the markets and a new Bull Run is taking steps with new leaders. The old war horses will either start to massively underperform or will move sideways for years to come. We have seen this in the past as well. The technology stocks did nothing for the first decade of this century after running up all the way to moon and back- Microsoft, Infosys and for that matter even HUL went nowhere for a good 7-8 years period. Similarly, Reliance went nowhere between 2007-14 while ITC has only recently begun to crawl.

So my bet is that the current lot of quality stocks- Asian paints, Berger, HDFC twins, Bajaj Twins etc will languish while the hot stocks such as IRCTC, Apollo hospital, Page etc will either fall 50-70% or will do nothing for the next 5 years. The game has moved on and so shall we.

As far as the new age companies are concerned – Paytm, Zomato et al are still hugely expensive and will go down at least 50-60% from here. The only thing I managed to learn from this carnage is that our MF managers do nothing special but to buy what’s going up! I used to admire Ramdeo Agarwal a lot for his conviction and quality picks. However, when I realised he has been buying Zomato and Policy and such a lot just because they’re moving up and came out on TV to justify the same, I lost quite a bit of respect I had for him.

In a market where junk flies the highest, the temptation to buy is enormous. I remember being asked if Zomato is a good buy and after having said no it’s not, to be almost mocked because the price went up 2x in three months. Well, I’m happy that I didn’t succumb to any such feel good story. A lot of people who thought Paytm is a great buy at 1200 or at 800 or even at 550 are yet to learn history lessons taught in the case of Yes Bank, Jet Airways and Suzlon.

Coming back to the Adani deal- I sense this massive $10B deal will formally mark the end of this commodity/metal/cement run in India. As I’ve iterated earlier, all these deals mark the end and not the beginning of a massive up cycle. It will be interesting to see how Adani group stocks fare over the next one year or so.

ITC has been the story of this correction. I’ve sensed in an earlier blog that maybe it’s ripe for an upswing and that feeling is being proven correct. The fact that it’s up 20% when the market is down 20% in itself shows which way the wind is blowing. Reliance too seems to be ready to lead this rally.

Some of the great stories such as Insurance, Credit cards etc were massively overpriced throughout the past five years. Similarly, Dmart, CAMS, IEX etc were beyond the reach of any sensible investor. I reckon in two to three years, some of them would be reasonably priced, just the way HDFC AMC is trading below its listing price after four years of IPO. This market may give us some opportunities in the near future.

As is our ritual, let’s talk about what I’ve been reading- Ambani and Sons is a fantastic read for anyone to understand how India looked 30 years ago and how privileged we are to not be living in those times.

PS- here’s a video from October 2008 when the world was literally falling apart. https://youtu.be/dcA9zGoAUhM

It’s interesting to see what our heroes talked about when they didn’t know if the world would survive. What stuck me is the ticker price showing Bajaj Finance at 50, ACC at 400 and Bajaj Finserv at 130! Now in hindsight it’s easier to say oh everybody knew Bajaj Finance is such a great stock. How many actually bought it at that price is the real deal!
Weekend musings!

A lot has happened in the past week. Both the US and Indian markets have fallen sharply following rate hikes by global central banks to address the rising inflation challenges. As you know, I don’t worry about the macro scenario so will not spend much time on what we already know- volatility is the nature of the beast and markets will move up or down for whatever reasons. Today I would rather talk about three things- startups, Reliance and of course the overall scenario!

The past six months have been brutal for new age tech companies across the globe. Be it our Paytm and Zomato or doordash, zoom etc in the US. Paytm we all know is going to zero very fast and is now joined by Zomato which is down roughly 66% from its all time high and over 50% from listing price. Zomato is now finally selling for the price of 1kg tomato! The beating in the US is much worse- Zoom down 75%, PayPal down 75%, Ark ETF down over 75%, the mighty Amazon down over a third and the list goes on and on. The idea that only tech will survive and everything else will forever stay in the dumps is being challenged.

Closer home, I was wondering how these startups find a way to lose money in businesses where making money is guaranteed by the nature of the game. In stock broking businesses, whether you buy or sell, lose or win, house takes a cut, period. Thus we are betting heavily on Isec, BSE etc. Now you have newer players like Groww and Upstocks funded largely by private equity losing money to attract customers! Wow! It’s like the Umpire in a cricket match getting out LBW! It sounds incredulous but true. The full year revenue for Groww is hardly 5cr rupees and it boasts one of the highest retail customers! So basically it’s a casino which allows people to gamble on its own account so that it can claim higher footfalls! Incredible!

Similarly, I am amazed by the way these grocery and food delivery companies operate. They deliver free of cost on the same day, some even in a few hours and charge much less than the retail price of fruits, vegetables or groceries and offer cashback! Wow! I mean, the smallest of the fruit vendors makes at least 30% on his cost and these supercharged masters of the universe lose money! How beautiful! Of course as a consumer I am delighted with their services but would never invest in their stocks.

Let’s now discuss Reliance! If ever there’s a company which embodies scale, this is it. The annual trunover for the whole year FY2022 is over $100B! Its profits for the year is over 67000 crores which is higher than sales of almost 99% of the listed companies in India! In an earlier blog, I mentioned how Reliance can grow to almost a Trillion Dollars company (https://zerotomillion.business.blog/2022/01/10/is-the-new-amazon-amongst-us/) Reliance retail is now doing annual sales of 2lakh crores! Just for reference, let’s compare it with other much more fancied retail chains- Titan did around 29k in sales and 2200cr in profits. Dmart did similar sales with around 1500cr in profits. Titan has a market cap of 2l crore and Dmart is at 2.4l crore, even after 40% correction. Reliance retail did 2l crore in sales and over 7000 crores in profits. This is twice the combined profits of the two behemoths. Take a deep breath and absorb this fact!

Airtel has annual profits of close to 5000 crores and sales of roughly 1.1l crore in the trailing twelve month period. Jio did sales of 95k crores and net profits of over 15k crore! Almost 4x of Airtel. And Airtel has a market cap of 4l crore!

So once you add Reliance in your portfolio, you basically have Titan, Dmart, Airtel, ONGC, speciality chemicals ( Reliance is one of the largest petrochemical companies in the world) at a market cap of 17l crores which is a steal compared to the valuations market is according to some of the stocks I mentioned earlier. I was all too happy to add some of it when Russia invaded Ukraine and it fell back to 2200 types.

Investing requires us to be patient in times like today’s when the bluechips fall massively and begin to underperform, markets trade sideways for months together and there is pessimism all around. What I do is to read more. I recently finished the Ambuja Story, autobiography of Narottam Seksaria, the founder of Ambuja Cements. It’s a fantastic read about someone who dared to dream big in the 70s and 80s in a socialist India. Anyone who believes India is in the doldrums needs to revisit where we were 40 years ago and how we survived the ugly days of state control. You may also like to pick Ambani and Sons by Hamish McDonald which chronicles the story of Dhirubhai Ambani. These two gentlemen are first generation entrepreneurs in days when India was a hungry third world country. In one generation, both of them became Billionaires. This is what I believe – bet big on India, it works! https://zerotomillion.business.blog/2021/05/24/bet-big-on-india-it-works/

Market whispers!

It’s 2007, the world is in a multi year commodity bull run led by China’s insatiable demand to construct now what we know as Highways to nowhere. Fuelled by higher share prices and soaring profits, Tata Steel acquires Corus, the UK Steel major. Hindalco acquires Novelis, another major global alumina giant.

It was anticipated that China’s rise at the breakneck speed of almost 10% per annum is the new normal. All major commodities, ferrous and non ferrous traded at lifetime highs. The music was getting louder and the party seemed unstoppable.

Come the 2010s, the world is still reeling under the aftermath of the global financial Crisis and the China story is shaky. People are beginning to whisper of a hard landing in China, metal stocks are down and both the deals which were touted as arrival of India on the world stage are now being found wanting!

It took Tata Steel almost a decade plus to cross its highs made at the top of 2007 bull run and for the entire period, most metal stocks were shunned altogether by investors. This is typical of all deals done at the top of the metal cycle. What I believe and sense is that the end of the current bull run in metals might not be too far away..

Recently, Holcim announced its intention to dispose of it’s stake in Ambuja and ACC at the tentative deal valuation north of $10B. This was followed by media reports claiming interests from JSW group and Adani group to bring the cement companies under their fold. What is interesting is that JSW plans to fund part of the deal by mortgaging some of it’s stake in JSW Steel and JSW Enegery, both shares trading at decadal highs, fuelled by this post Covid commodity dream run.

History rhymes, if not repeats itself. The stocks of old economy stocks such as Steel, cement etc were shunned by investors for almost a decade before making a splendid comeback in the latter half of 2020. Experts are lining up to urge the public to allot major parts of their portfolios to metal stocks as they promise rising profits and higher dividends.

Once the cycle turns sour, the profitability of metal and all commodity stocks goes down sharply as most of them have very high fixed operating costs and margins vary wildly based on current market prices of the underlying commodity. Like it or not, the deals are done mostly at the top of the cycle because that’s when balance sheets look strong, it’s de-leveraged and analysts are more likely to assign a higher EV-EBITDA valuation.

Howard Marks has highlighted this in his fantastic book Mastering the Market Cycle. It’s illuminating to see how investors are extremely greedy at the top of the cycle and horrified at the bottom. The key in investing is to be the opposite – be fearful when others are greedy and be extremely greedy when others are running for cover.

It’s going to be very interesting to see how this story unfolds!

The Big Picture!

Today I would like to talk to you about two kinds of people in India. The first kind are the learned class, the intellectual types with good degrees and plush jobs, the kind you can find in offices around you. If you ask them- is India growing/getting richer/ on the right track? The first reaction would be a 😏.

If you probe them any further, they’ll tell you everything that is wrong with India. High inflation, joblessness, growing social tension, higher crude and commodities prices, rising inequality etc. This is the standard answer I generally get from most of my colleagues. And to prove their point, they’ll give you data and reports in droves, especially from the “reputed” international organisations and non-profits such as Amnesty, UNHRC etc.

What I generally ask after this is if they’re investing their money in stocks. More often than not, the answer is that hardly a part of their net worth is invested in equities. The two aren’t interrelated and am not drawing any conclusions but are just a reference point for further discussion.

On the other side are some people who are perma- bulls. Here’s a speech from Gautam Adani who said India is likely to eradicate poverty by 2050 and can have a $28-30 Trillion economy by then. A back of the hand calculation shows that it assumes an average growth rate of roughly 8% over the next 28 years. Here’s a link (https://twitter.com/ETNOWlive/status/1517145792594968578?t=Icdo1Qp89btcZdPUw1AmUQ&s=19)

The moment you tell these things to the first kind of people, you’ll be mocked, ridiculed and possibly shunned altogether. They are going to quote experts and organisations and who’s who or everywhere as to why India is never going to grow that large and why we’re not even growing right now and all the data published by the Govt which says we grew at 8% last year is a sham and what not.

Now here’s my take on this. If you ask them how many companies these experts run or have created? The answer is Zero. How many of such experts are self made millionaires, the answer remains to be zero. If you also ask them if any of their types even believed India was likely to survive the Covid pandemic, the answer still remains to be Zero. I call these experts Doomsday predictors. Fortunately, they don’t matter.

If you follow any of their advice, you’re most likely to never bet on India and will forever stay off from investing in the humongous wealth creation we’re likely to witness over the next generation. Choose your gods wisely.

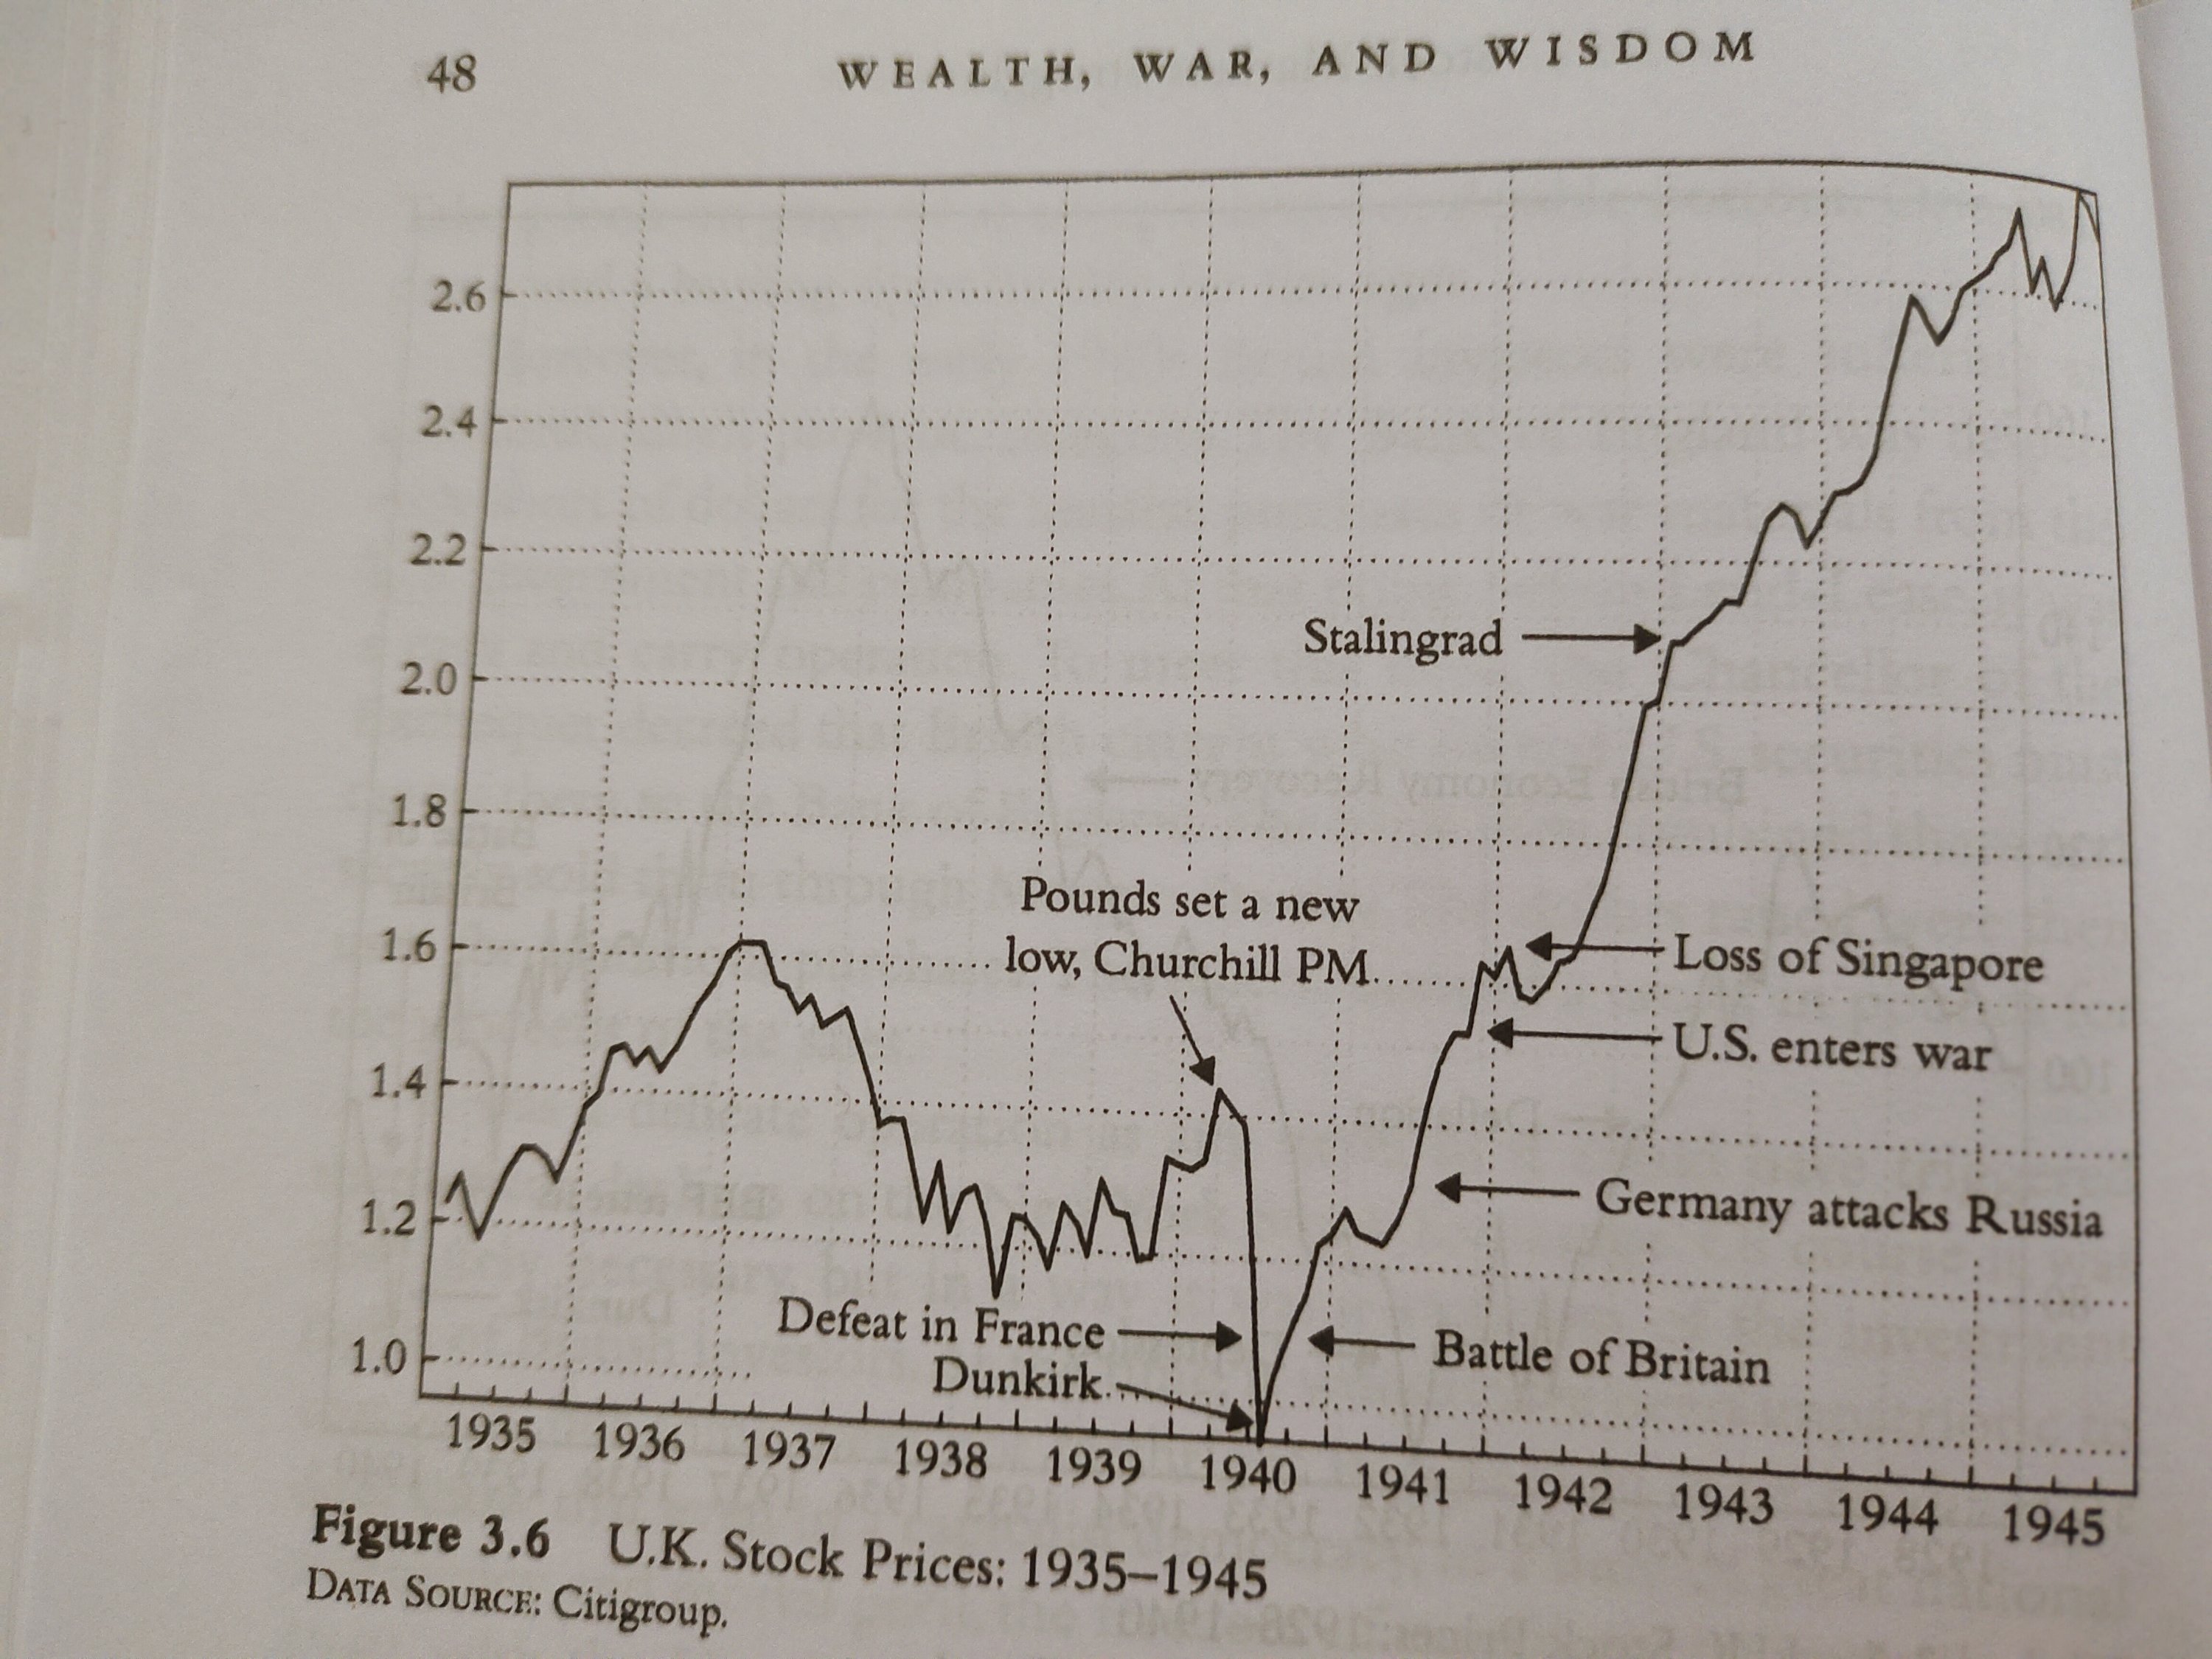
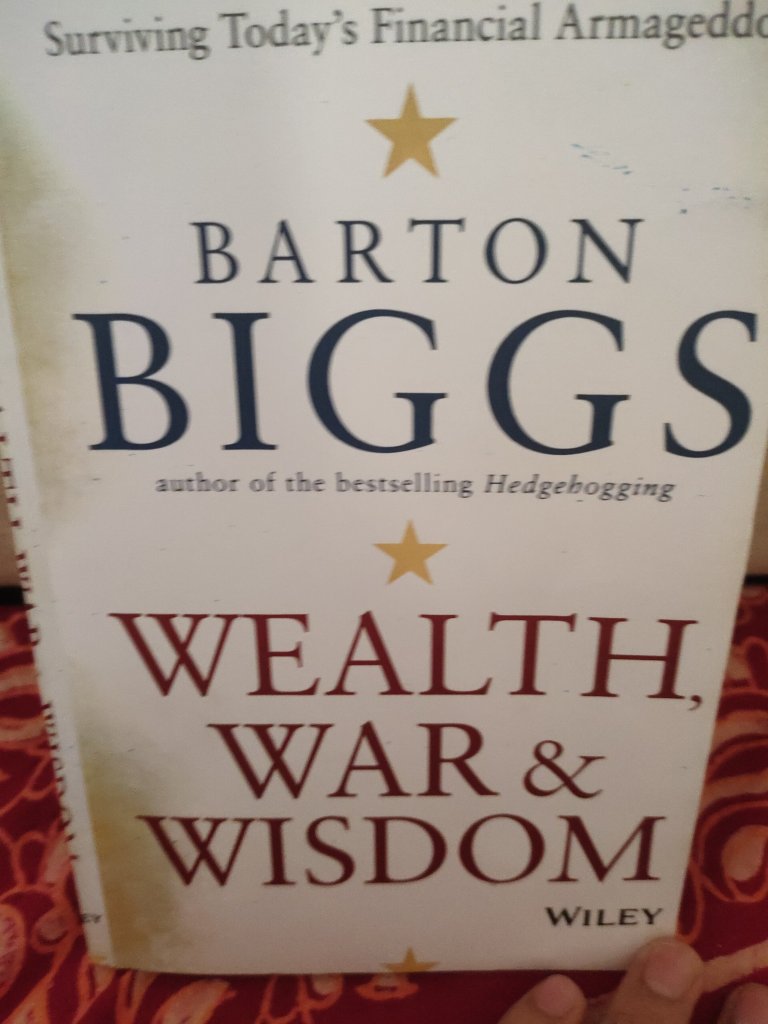
Let’s talk about another idea. I’m reading this book about the performance of equities during the second world war.

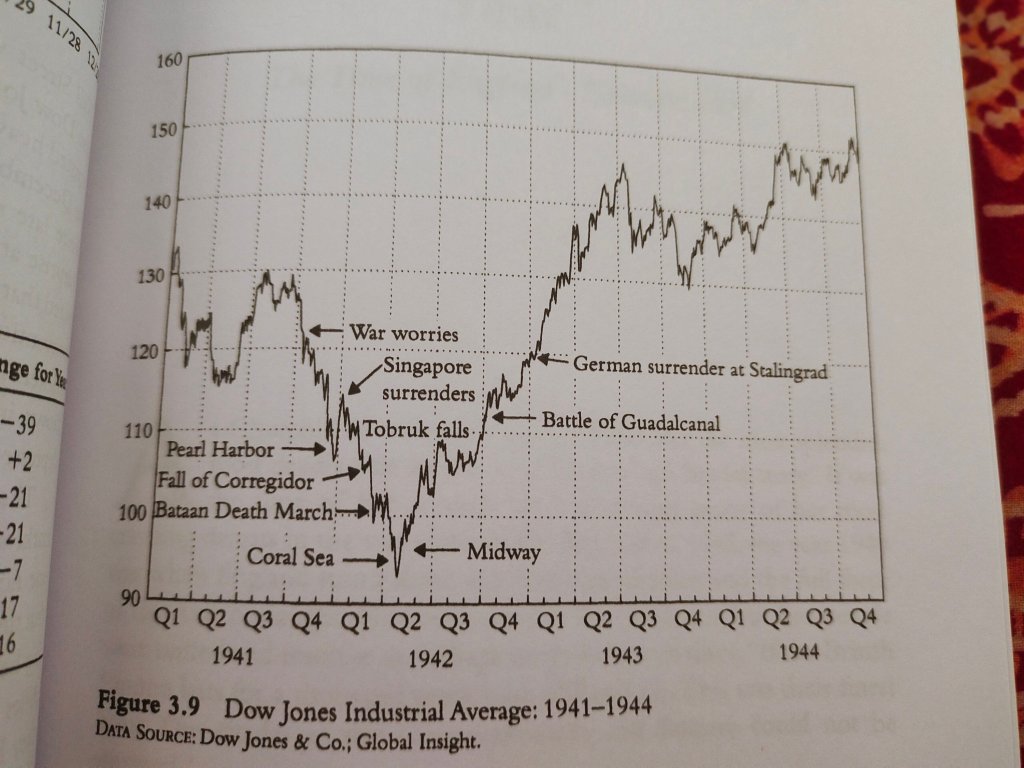
The most interesting thing which I took from this is that surprisingly, US, UK and German markets could sense which way the war was heading before even the generals and the political leaders knew. The UK market bottomed in 1940 when Britain was the weakest.The German market made its top much before their armies had even faced a significant retreat, much less a defeat and similarly the US market made its bottom when everyone knew that the US was losing the war. Take a look below:

The important takeaway is two: market bottoms are made at the point of maximum pessimism i.e. when you’re fearing apocalypse. After that, the market moves up not because the news is good or better but because it’s less bad than what is already known. Similarly, market tops are made at the point of extreme ebullience. Once that point is reached, it can only get worse from there.

It helps us understand why the market made its bottom on the day of the first lockdown in 2020 and not when the damage was done two months later. It also helps us understand why on February 24,2022, the recent panic low was made.

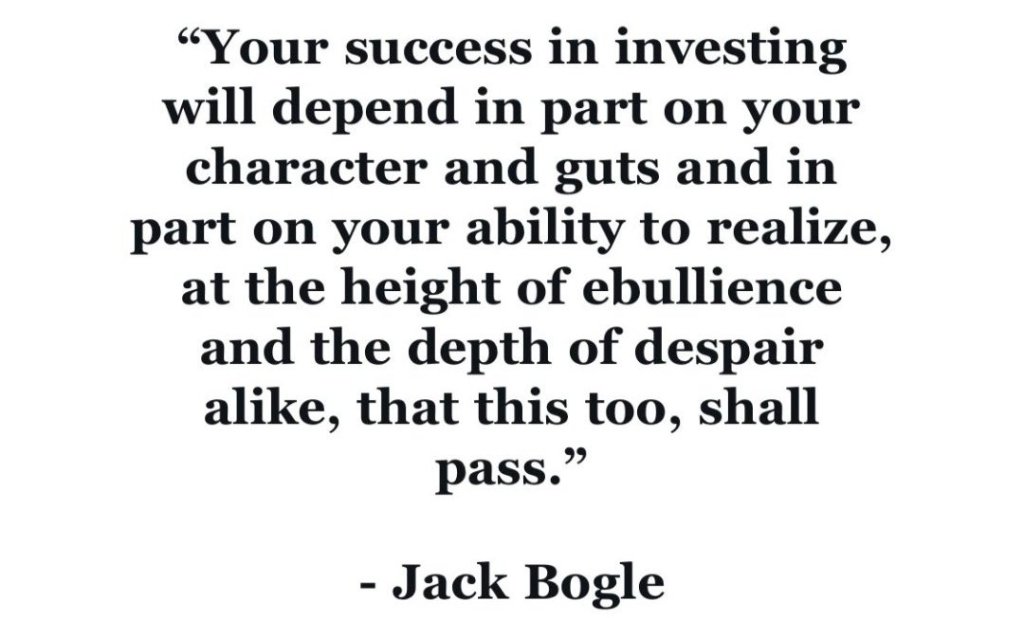
The point I’ve repeatedly made is to buy heavily when the markets fall and buy your heaviest when the world is collapsing. Here’s what Jack Bogle had to say

This sums it up the best!

PS: Since we are discussing experts, let’s also discuss the stock market gurus we watch on CNBC and on twitter. On April 4, when the merger of HDFC with HDFC Bank was announced, there hardly was anyone who didn’t go ga ga over the brilliance of the move. Every channel and its anchor and every expert worth his salt came out and said, the days of HDFC group’s underperformance are over and the upswing is just the beginning. They explained in detail how this will lead to low cost of funding and finally take the shareholders to the proverbial land of milk and honey.

Cut to yesterday, both the HDFC and HDFC Bank are down 15-20% from the merger day’s high. The same experts are now justifying why the merger isn’t that big a deal and why the group is likely to continue to under-perform over the next two years. So much for market genius!

Try watching this on YouTube by digging into the library of CNBC TV18 or just typing HDFC Bank merger news. It’s funny!

What are we seeing!

Today’s market was funny. Reliance is trading close to it’s life highs while the HDFC group is underperforming big time. Similarly, ITC is getting its groove back while HUL, Nestle and Britannia are going nowhere. So what’s happening!

My sense is that there is a slow but definite churn in the market. If you follow the nifty index constituent weights, you’d have observed that Reliance is now almost 12% of the index, while for most of the last three years, it hovered around the 9-10% mark, closely followed by HDFC Bank. HDFC Ltd is not in the list of top ten companies by market cap while ITC is over 3.1% of Nifty 50. HUL which was almost 4% is down close to 2% while Nestle and Britannia have returned close to zero over a 2 year period.

The high of the last bull market was the corporate tax cut in September 2019. If you take returns of the market darlings from that date, the returns are much less than the market. NIFTY 50 is up over 55% while Nestle is up just less than 25%,HUL is hardly up 10-15%, HDFC limited is at the same price it was in September 2019 while HDFC is up just about 10% . Reliance is up over 100% over the same period.

What is happening is that the law of averages is catching up with the erstwhile quality must own stocks. This has happened in the past and will happen again. We’ve heard this multiple times that every bull market is led by different leaders. Similarly, this won’t be led by the HDFC pack or the Nestle and Levers of the world.

I read somewhere that the only thing new to learn in markets is the history we are yet to read. Everybody who is perplexed by what’s happening in the market must go back and read market history. In the Indian context, there’s a quick and witty book by Santosh Nair titled- Bulls, Bears and other Beasts. Read it and you’ll get some perspective.

In a market which is now down ten percent from its highs and has languished with relentless FII selling, Ukraine war, rising inflation and what not, the best way is to do nothing. The stocks you own are minority stakes in living businesses and a business does not lose ten percent of its value in a day.

What we are seeing is massive crowds thronging the marketplaces, highest ever exports, long queues to buy premium cars, movies making 1000 crores and sold out hotels. If you don’t believe me, just try going out on a Friday night and count the luxury cars you see in Jaipur or any other city, try to find a parking space in any mall or try booking a hotel for a weekend getaway. Of course if you ask the experts, they’ll scare the hell out of you. Well, which of the experts you know drives a Jaguar? None and that’s the point!

What we are seeing is a growing number of people paying a premium to join better gyms, shopping more and from the higher end brands and the erstwhile luxuries are the new necessities. I personally didn’t own an AC until two years back and since then, between me and my in-laws have purchased 6 of them and everything you want to buy is out of stock! A friend of mine is waiting for three months to buy his automatic Nexon and the reason is not the semiconductor shortage but real demand. Anecdotally, people are using connections to get their hands on a new Tata car by leapfrogging others in the waiting list.

What we are seeing is that the organised retail is shooting through the roof and this I have experienced first-hand, having purchased clothes and toys for my newly born niece.

To experience the above, you don’t need an expert. Just open your eyes and look out. India is growing richer. There’s a reason why Reliance is trading at life high in this down market!

Investing is a loser’s game!

I recently completed this fantastic book called Invest like a Dealmaker by Christopher Mayer. It included the captioned quote from another investing legend which basically means successful investing requires one to avoid making mistakes and make the most of other people’s mistakes, as in amateur Tennis where all you need is to roll the ball over the net to keep going. This is unlike a winner’s game such as professional Tennis where you need to be skilled enough to win on your own.

So today I look back at some of my mistakes, flops and disasters which toughened me enough to keep going.

It was early 2018 and I began to invest in a company called Reliance Home Finance. Yes, ADAG group of all things. I prided myself on having read the Intelligent Investor and had recently learnt to read the Balance Sheet. My first investment was made at 107 and when I finally got out in March 2020, it traded at the princely sum of 95 paisa! I lost 99.99% of my money and a total loss of over 1l. So what went wrong?

First of all, I bought junk which turned into shit. I didn’t care to see that the group had begun to default on its other debt obligations and claimed foul that it had nothing to do with its own shortfalls. Funnily, I kept hinged on its book value which was over 50rs at the time of my purchase. One lesson I learnt was that a lender’s book value can vanish overnight when debt came calling and it had nothing to pay. This did happen and once its asset value went south, book value meant nothing!

Secondly, I learnt to never buy junk! In a world where you can choose from 5000 stocks, why waste your time praying for a bad group to turn out sober.

Another huge flop for me was Yes Bank. I lost almost 99% of the invested capital for similar reasons as mentioned above. I remember the sigh of relief when I could exit at around 8Rs in March 2020 that at least my portfolio was cleaned off all the shit I carried in the name of Value Investing.

Here are my takeaways( https://zerotomillion.business.blog/2021/05/26/dont-buy-junk/) It is of utmost importance to avoid losing money. This does not refer to the notional stock price decline which happens as a matter of fact. Loss/ Risk is defined as the possibility of permanent loss of invested capital. So once you learn the art of saying no https://zerotomillion.business.blog/2021/06/12/art-of-saying-no/, you narrow your list to such stocks which have at least more than a fair chance to survive and thrive over a three five year period.

I also made a thumb rule to avoid lenders. This goes against the investing wisdom prevalent in India where Banks form almost one third of the key indices and HDFC Bank and Kotak are touted as the cornerstone of a sound portfolio. Well, why I differ is that I hate businesses where you call a sale as money going out of the door. This is exactly what happens in lending businesses. You borrow short term deposits, and lend long term, praying for money to come back on time,if at all. What I love are the non lending financials. They are the cash generating machines. You can’t trade without putting in the full amount needed with your broker and win or lose, he makes money. The MF guy takes his cut before he invests on your behalf. BSE gets the cut irrespective of the market moving up or down, every day of the year when the market is open! I simply love them!

The fact that I could learn to buy them and didn’t fall for a PNB which my broker almost begged of me to buy at 60, and again at 40( now still trades thereabouts) or a Jet Airways is because I booked that loss of over 2l which by the way still shows in my ITR. I learnt to book a loss as it cleans up your portfolio and also is tax efficient. Your loss can be carried forward up to 7 years and is set off against equal gains made subsequently. Also, booking loss is painful. So next time you’re very careful to avoid such traps.

I also have learnt to give up on the idea of beating the market. Every great Investor who has survived the game for over 10 years tells you that he has lagged the market for multiple years in a row but one or two great years eventually make up for everything. Also, concentration is essential. You can’t win big by betting 1-2% on your best idea. Unless you back up the truck on your best idea and see it grows to almost 50% of your portfolio or even more, it won’t make a difference to your networth( https://zerotomillion.business.blog/2021/06/07/growing-your-capital/)

PS: one stock which I followed quite closely, bought and then got out is Care ratings. It ticks all the boxes, Guy Spier owns it, Crisil bought 9% at 1600, business is strong. However, I just couldn’t add to my portfolio as whenever it fell further, something like an ICICI SECURITIES also fell. Everybody except Buffet runs out of cash buying the dip. So I thought it was wiser to add to an already substantial position of an ISEC or TaMo rather than trying to create a new position in Care. This is a lesson on capital allocation one must learn- you only have so much money. Spend it wisely!

The Holy Grail

We all have heard investing folklores of how if you have purchased Eicher shares instead of buying a Bullet motorcycle, you’d have enough to own a BMW or if only you had bought TCS in the IPO, it would have made you a millionaire. The idea is to underline how stocks can generate wealth for those who own them.

If I try and define the holy grail in investing, it’s going to vary person to person. Someone would say beating the market year on year is the ultimate objective whereas someone would define it to be able to make a quick 20-30% on invested capital. However, I define the ultimate objective in investing is to own stocks in a company which you don’t need to sell to book a profit. The stock should just lie patiently in your demat, going up atleast 10-20x in 10 years and returning multiple times of the original capital as yearly dividends.

Now you’ll wonder, does this thing really happen in the real world to people like us. The answer is, yes it does. It not only happens to someone like a Rakesh Jhunjhunwala who owns over a Billion dollar stake in Titan at an average price of less than 10rs and whose annual dividend would be much higher than the amount he invested. It happens to people like us too. Look around for people who owned small shares of Hero, Reliance or TCS and forgot to sell. The shares have gone up more than 500x each with an annual dividend much higher than what they put in to buy those shares.

Also, investing is not about beating the market. This is the one myth which needs to be busted and buried. I’ve gone up more than 5x since the end of 2019 and over 3x since August 31,2020 at a consolidated portfolio level. If I was just trying to beat some arbitrary index, I’d have less than half my net worth today. I stumbled upon this fact almost accidentally. Those who know me closely know that I keep a journal. Going through old logs, I realised my portfolio has gone up more than 100% annually in each of the last two years, of course with some additional capital which I invest. However, this proved to me that going up from 1x to 4x is real and doable.

Our mind is accustomed to thinking in straight lines in terms of growth. So if we have 10l, we think it might grow to 12/15/20 in some years. However, compounding is a different beast. It begins to grow exponentially which our mind can’t fathom. So for someone investing 10l, it’s extremely different to think how her portfolio will look when it crosses 1cr. Similarly, we can’t even imagine what can happen if some of our stocks go up 10-20x.

I’ve previously discussed what Nick Sleep achieved in Amazon or how Jhunjhunwala simply sat on Titan and became the billionaire he is today. This thought was recently reinforced by a brilliant book called the 100 Baggers (image below)

I strongly recommend everyone to buy and read this as soon as possible. The idea enumerated is how we should aim to own stocks which can possibly go up more than 100x from their initial invested price and how this is the best way to generate wealth. Like Mohnish Pabrai said recently in a recent video- the idea is to find a CRISIL and go to sleep for ten years. Once you own something which has a huge runway ahead, the best thing is to leave it alone.

Another book by the same author which I’m reading is called Invest like a Dealmaker. The idea is that while valuing a company, you should look for what another company or a person would pay to buy the entire company in question in a private transaction. This helps you to think in terms of owning minority shares in a business and not just look at the quoted stock prices we observe on our screens.

My learnings over the past two years have been to identify businesses which have a huge runway ahead of them in a growing India, are on the right side of technology and fall either in a rising consumption by a richer Indian middle and upper class or higher investment by the same people. This helps me avoid a lot of companies and saves a lot of work. Further, by using the art of negation, I also avoid anything which I can’t understand without a calculator or with my already developed knowledge base. If I have to read computer programming to just understand a company’s business model, I’m best served by avoiding the stock.

On top of this, which I have articulated in earlier blogs, what I now am looking for is businesses to own forever. Of course, forever seems too far stretched but the idea is to not even worry about price movement, favorably or adversely. I was actually happy when TaMo recently fell 30% as it helped me add to the already built position. Similarly, I fail to understand how ISEC is available at this price. All of the stocks I currently own, including Hero are here to stay.

So combining the two, we should aim to look for businesses which can flourish over the years so that not selling remains the best idea. Further, in order to get over the anxiety of stock prices going up and down on a daily basis, we should always value the stocks as minority ownership stakes in living companies so that our vision aligns with those of the management. I was very happy when a few days back my father told me that we may possibly have to never sell BSE. He owns few shares and has seen it grow 5x from his price. I fully agree with him and like I always say, my BSE shares are not for sale.

PS: Here’s an update on what I wrote about Hero in the last blog- The IT raid story died soon enough and if there’s one news we all must follow is that of EV two wheelers of a lot of brands catching fire across the country in multiple incidents. This makes life of someone like Hero Moto much easier as who would buy an Ola or Okinawa which catches fire. Trust is the most important constituent in mass EV adoption. Also, Ather is almost 40% owned by Hero and there have been no such incidents reported against Ather. Thus, my thesis stands.

Random Musings

The new FY is here and we’re trying to figure out how markets are likely to behave and how our returns are likely to be going forward. So here I am with my two cents:

We’re also celebrating two years of Covid lows and the recovery in the markets has been truly stunning. If we see how many people were willing to buy if they got March 2020 prices vs those who actually bought when markets collapsed on Ukraine scare, the difference is stark. I have made this point before that news and prices are almost inversely related. When you see green on the screen, the mood is good, headlines are upbeat, the prices of stocks are more likely to be higher than what you ought to pay for them. On the other hand, when the news is that of an impending apocalypse and the world is going under for some or the other reason, the prices are most likely to be most favorable to buy.

However, ask yourself if you followed this advice in last week of February 2022. Nifty was bleeding and stocks were trading at a discounted price. But we were scared to buy because the news made us believe that the world is coming to an end. We were going in for a nuclear war and WWIII and what not.

Investing requires the vision to see, courage to buy and patience to hold. Of the three, patience is rarest among investors. Unless you systematically train your mind to ignore the news- the Fed, interest rates, Russia Ukraine, elections etc and focus on the underlying business of a company who’s stock you have bought, you will make decisions which are injurious to your wealth.

Now let me talk about some things which I have been thinking about. Recently, you must have heard Nitin Gadkari about reducing EV prices and also that he used a Hydrogen powered car to come to the Parliament. Also, we see there are almost half a million Government cars which are likely to be replaced by EV. Everyday some or the other company is either talking about installing charging stations or making progress with battery. Now add to this that TaMo has sold it’s highest ever 3357 cars in March 2022. Just imagine the runway ahead and the kind of sales it can generate in years to come. TPG values it’s EV unit at $9.5B and today the entire company, with PV and CV unit trading at around $22B only. This is a no brainer where this stock is likely to be headed.(https://zerotomillion.business.blog/2021/10/13/hello-tata/)

Reliance is making numerous acquisitions in retail and Renewable energy and the thesis which I laid out in my earlier blog https://zerotomillion.business.blog/2022/01/10/is-the-new-amazon-amongst-us/ is being played out. Reliance is now almost 12% of nifty 50 and my bet is that it will continue to outgrow a lot of other large caps.

Over the past one year, I have moved away from cyclicals and commodities towards what I believe are beneficiaries of the larger India story. This has proved extremely beneficial in some and not so in others but am happy to add to ISEC and HDFC AMC as I believe they’re not three year stories but 15 year stories with a huge runway ahead.

One more thing I wanted to write about was this two wheeler EV catching fire recently. Ola, Okinawa and one other scooter was recently in the news for this reason. My point is that once the legacy auto makers- Bajaj, Hero and TVS comes in all guns blazing, the new kids will either fade away or merge or die. The analogy in this regard is the smartphones market in India. Not too far ago, we had brands such as Lava, Micromax and Karbonn. They all were cocky enough to poke the Samsungs and the Apples. However, once the economy of scale was achieved in the ecosystem, none of them could compete against the better equipped players such as Vivo, one plus and Oppo, coupled with Apple and Samsung.

Similarly, I believe in a couple of years, we’ll see some of the new entrants fizzle out and market being dominated by the players who deliver not just the product but after sales and service. Ola can claim to build a superfactory but how will it service customers in smaller cities? My bet remains Hero Moto as it also own a large chunk of Ather Energy.

PS: the recent news about bogus transactions by Hero seems far fetched to me as someone like Pawan Munjal who has run this company for 30 years and prides itself on paying highest tax and has a great dividend history , do you think it’ll destroy the name for some farm house in Chattarpur. This I believe is a non issue and the matter will subside in a few days. This might play out like the whistleblower complain in Infy when all it turned out to be was a great buying opportunity!

Reverse compounding!

So with today’s fantastic run, Paytm is down to around 38k crore market cap or roughly $5B in dollar terms. So from IPO price, it’s down over 72% and is possibly one of the fastest minus 1l crore market cap in India’s history. This also values it the same when it raised money back in 2016. So anybody who came and put money in its subsequent funding series is underwater. This my friends is called reverse compounding and is deadlier to your networth than you can imagine. See – https://zerotomillion.business.blog/2021/05/26/dont-buy-junk/

First, my views on Paytm and its siblings have been consistent all through its journey to hell- see a link to an earlier blog , written in November ( https://zerotomillion.business.blog/2021/11/19/paytm-mat-karo/)

Second, in addition to what I wrote as to these fintechs are trying to achieve through cross selling and data selling is somehow be able to lend money by becoming a Bank or an NBFC or even an SFB. Now let’s put this to my logic test.

In India, who goes to avail loan from a paytm or likes? The one who won’t get a penny from his family as this fellow trying to avail 1l or 50k personal loan has basically no to little income, has no intention or inclination to manage personal finances well or else they won’t need this money in the first place and also, have little by way of a decent credit score or else their own banks would have extended similar loans at much better rates. These are people trying to fund an iPhone, or a Thailand trip or other fancy stuff which they certainly can’t afford in a better world. They’re like the infamous NINJA- No Income, No Jobs and No Assets loans in US which fuelled the fire once housing went bust.

Now lending is inherently a risky business as you’re never sure if your money will come back on time, if at all. On top of it to extend loans to such class is a sure shot recipe to disaster. Now let’s extend this logic. Even if they go on and extend enough loans somehow and acquire an NBFC or a Small Finance Bank license which in itself is far fetched, considering the myriad corporate scandals which keep coming out, they will be valued to price to book basis. The premium Banks like HDFC and ICICI trade at 3-4x price to book( equity book, not loan book) and extremely premium NBFC like Bajaj Finance traded at 8x Price to Book. So at max these companies can trade at similar levels. Now here’s the catch- thanks to the accumulated losses on the way,the moment they turn to profits, their capital will erode in order to clean up the mess. And that will make book value at max Zero from negative. And in such case, their price to book at whatever level will make the price, well, ZERO!

So even if they turn victorious in their Gods work they claim to be doing, the share price is eventually going to be zero.

Here’s my takeaway- one Yes Bank or Jet Airways or a Paytm a year or two can turn all your gains vanish and portfolio returns negative. So avoid junk, even if it’s for free. The first principle to make money is to avoid losing it. Say no to ideas which makes no sense and are just fancied in the markets.

( https://zerotomillion.business.blog/2021/06/12/art-of-saying-no/ makes similar points)

BSE- The game is on

It is an unbelievable rally in this stock, up almost 5x in a year, most of which has come in the past ten trading days-up over 60%! This seems surreal, even though I have been a big votary of its value realisation. See my earlier blogs( https://zerotomillion.business.blog/2021/05/26/is-bse-the-new-game/, https://zerotomillion.business.blog/2021/11/16/nse-beckons/ & https://zerotomillion.business.blog/2021/12/15/bse-is-the-new-game/)

However, when it cruised past 3000 and momentarily above 3100 intraday today, all I wanted was to burst out with joy but then decided to silently pat myself on the back and hold my emotions. However, when someone asked me ” aur kitna jayega”, I reply with my usual- it’s just started.

The more I read about stocks which went up in a Bull run, the more I realised that the worst mistake is to fold too soon in a rising market. For someone who bought Bajaj finance after its first 5x move from 2014 basically missed the next 10x move. In absolute terms, the money made in every double is more than the entire sum made earlier and this is the key. We’re not here to make money in percentage terms but to become millionaires in real terms. If you invest 5l and it goes up 3x, you’ve made 10l profits. However, the next 2x will give you additional 15l and that’s the key point to remember.

So how am I feeling today after this massive run? Well, it’s over 40% of my networth and I keep going back to how Nick Sleep must have felt when he put close to $10M in Amazon and saw it going up 20x and become over 80% of his networth/portfolio ( https://zerotomillion.business.blog/2021/08/10/building-an-investment-thesis/ )

For me, the shares of BSE are not for sale, not now, not ever. The idea to book profits out of a stock which has infinite potential to move up is the stupidest thing one can do. Ofcourse it’s coming out of a massive rally and at some point it too will fall, go through time and price corrections and everything else which happens in the market. However, I’m just too happy to have it for the next foreseeable future and beyond.

Let’s see what I believe is happening to this company. Over the past week, when markets went up around 3-4%, it’s up over 50% and with unprecedented volumes. And that’s without a shred of news or even rumor. This doesn’t happen often in market. Not on twitter, or in any media publication anyone has come anywhere close to even concoct an explanation. So what’s cooking!

My gut is that it has a lot to do with someone building massive position ahead of something we might see on NSE front. Now I’m only talking my gut here without any source or information whatsoever. What I believe is that there’s something to do with ongoing cleanup of NSE . The colocation scam is refusing to die out and the incumbent CEO is hanging up his boots. It sounds a lot like what happened with Yes Bank. Remember here that Yes Bank fell 30% in a day just on the news that Rana Kapoor wasn’t given an extension. There was no mention of any fraud or malpractices. We knew how it ended- down 98% in 18 odd months.

Now let’s take my logic test- here’s a company with over 5000cr net profits, growing revenue year after year with a massive lead over its only competition in equity derivatives and cash segment; grey market deals value the firm at over 2l crore and the CEO is basking in this glory. So why on earth is he refusing for a near guaranteed second term for five years? There are only two reasons possible – either he knows that the goose is cooked and want to leave with his reputation intact or he’s been shown the door by the regulator and in a face saving gesture saying he’s not seeking a second term. In either case, it fails the smell test.

Now take this a step forward. If NSE was a listed company, by how much would it’s share price fallen on the news that its former CEO was running a sham operation with a fellow who cooked up the dumbest email id for a yogi- rigyajursama@whatever.com( the userid is the three Vedas named consecutively). I mean this fellow didn’t even pretend to be intelligent. And to add, the incumbent CEO decided to quit. Well, Jubilant foods on the same news fell 15% today. And there are whispers of a SEBI refusal for any IPO in the near future and grey market valuations falling sharply. Couple this with the recurring technical glitches on NSE which doesn’t seem innocuous anymore.

NSE was created to bring BSE to size. The earlier BSE was a broker’s fiefdom. NSE was supposed to be the good boy ,a poster boy for India’s resurgent financial strength. However, the opposite has seem to occur. BSE has become the beacon of positive corporate governance and technical know-how. In almost all new products, BSE has beaten NSE fair and square. Be it commodities, INX at Gift City, mutual fund distribution through starmf, NSE hasn’t been able to garner any significant market share even after outspending BSE by a wide margin. And with its gold spot exchange and power exchange ready to commence, the blue ocean businesses are only going to take it from strength to strength.

One advantage BSE has was it’s miniscule institutional holding. This means now that it has performed well in a falling market, the funds- PMS, HNI and FII-DII will have to enter at some point to share the spoils lest they fail to explain as to why they never owned anything in a stock which has gone up 5x in less than a year. This means a lot more price stability on the upside going forward. Furthermore , it’s market cap is a paltry 13k crore even today. It’s not even a mid cap stock as per AMFI classification. Once it moves to the mid cap club, it’s impending inclusion by funds and indices, the real price movement, if it happens and I truly believe it will, surprise the most optimistic of us all.

Remember this, Bajaj Finance went up 50x in seven years when Nifty barely doubled. What a stock can do on the upside is beyond anybody’s imagination. Once you’ve hit a bonanza, the only thing which can kill it is you- by selling too early!

Stay invested, the India story has barely begun. If BSE succeeds in even getting a fifth of India’s energy derivatives and gold spot market, we don’t even know what gold we’re sitting on!